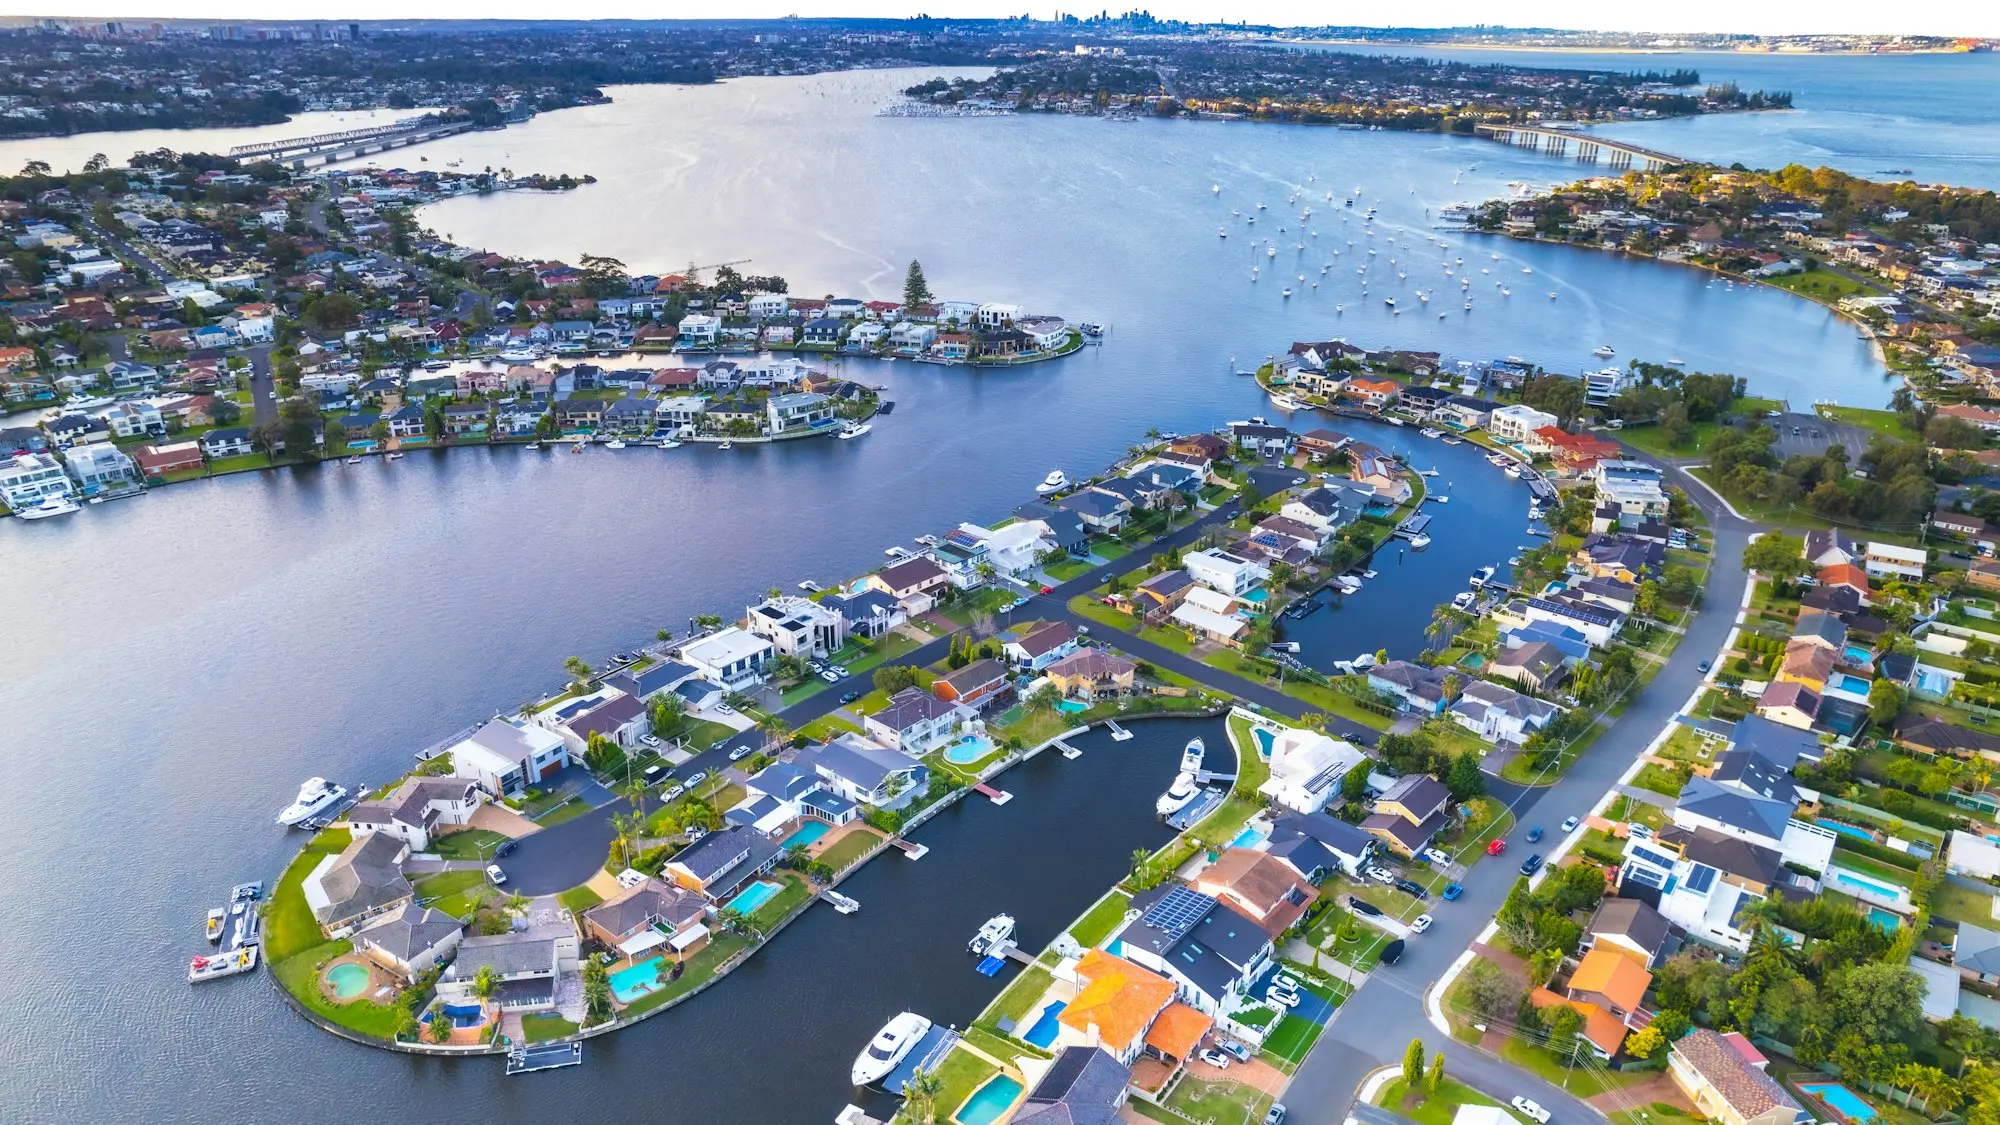
Quick answer
Our caveat loans are written on Victorian property. For Gold Coast property we arrange a short-term registered second mortgage, which does the same job: fast business funds behind your existing bank loan, usually arranged just as quickly. Homes, canal-front property, many apartments and industrial units in Yatala or Molendinar can all be considered, and Tweed-side NSW property is handled the same way.
Key points
- Gold Coast property is funded with a short-term registered second mortgage lodged with Titles Queensland.
- Apartments are accepted case by case; the building, the unit's size and how it's let matter most.
- Canal and waterfront homes are valued on nearby waterfront sales, not street averages.
- Tweed Heads and other NSW-side property uses the same structure, lodged with the NSW registry.
- Loans from $20k to $5m, business purposes only, straight from the lender.
- Structure
- Registered second mortgage
- QLD side
- Titles Queensland
- Tweed side
- NSW Land Registry Services
The Gold Coast has a property mix unlike anywhere else in the country: towers on the beach, homes on canals, acreage in the hinterland and a busy industrial belt along the M1. All of it can work as security for a short-term business loan. Our caveat loans are written on Victorian property. For Gold Coast property we arrange a short-term registered second mortgage, which does the same job, putting fast funds behind your existing bank loan, and is usually set up just as quickly. As the lender, we make the call ourselves.
Can you get a caveat loan on the Gold Coast?
You can get everything a caveat loan would give you. On Queensland land, the structure we use is a registered second mortgage, lodged with Titles Queensland behind your bank’s first mortgage. Titles Queensland lists mortgages and releases of mortgage among its mandated eConveyancing instruments for freehold lots, so both the start and the end of the loan are handled electronically.
Why is that better for you than a caveat would be? Because a registered mortgage is the standard dealing every bank, conveyancer and buyer’s solicitor expects to see. When you sell that unit or refinance that warehouse, the payout and release are routine. For a fuller comparison by state, see caveat loans outside Victoria.
Quick guide to how Gold Coast property is looked at:
| Property | What the valuer focuses on | Typical fit |
|---|---|---|
| Family homes (Robina, Varsity Lakes, Coomera, Helensvale) | Recent street and estate sales | Straightforward |
| Canal and waterfront homes | Comparable waterfront sales, frontage, pontoon, bridge clearance | Good; valuation may take longer |
| Standard residential apartments | Sales in the same building, size, outlook, body corporate | Case by case, usually fine |
| Holiday-let or serviced apartments | Letting pool terms, buyer depth | Harder; ask early |
| Industrial units (Yatala, Molendinar, Burleigh) | Access, hardstand, zoning, nearby unit sales | Strong |
| Hinterland acreage | Usable land, access, how saleable it is | Slower valuation |
Do lenders accept Gold Coast apartments as security?
Yes, many of them. The question isn’t “is it a unit?” but “how easily would this unit sell?”. A valuer working a high-rise apartment in Surfers Paradise, Broadbeach or Main Beach will check:
- Sales in the same building over recent months. More sales means firmer evidence.
- Size and layout. Very small studios have a thinner pool of buyers than a standard one or two-bedroom unit.
- How it is let. A unit you or a tenant live in is simpler than one locked into a hotel-style letting pool or a management rights arrangement.
- Body corporate health. Sinking fund, levies, any special levies or known building works.
If your unit is a straightforward residential apartment, it is usually acceptable. If it sits in a holiday-letting scheme, tell us at the start so we can check fit before you spend time on paperwork. More detail on what valuers look for is on our valuations for short-term loans page.
What about canal and waterfront homes?
Canal homes in suburbs such as Sorrento, Broadbeach Waters and Paradise Point are valued against other waterfront sales, not against the dry streets nearby. Frontage length, whether the canal is wide or narrow, bridge clearance to open water and the state of the pontoon or revetment wall can all move the figure. Because there are fewer close comparisons, the report sometimes takes an extra day. Order it early.
How fast can a Gold Coast second mortgage fund?
Speed depends on the same handful of things anywhere: the valuation, every owner signing, a current statement from your bank and evidence of how you’ll repay. With those in hand, a loan of $20k to $250k is possible the same day, and amounts up to $5m are possible within 24–48 hours. Holiday homes owned by interstate or overseas co-owners are the most common cause of delay, so line up every signatory first.
Got a Gold Coast deadline? Send us the details and we’ll tell you what’s realistic.
What about property just over the border in Tweed?
Tweed Heads, Kingscliff and the rest of the Tweed Shire sit in New South Wales, even though they share a skyline with Coolangatta. For property there, the second mortgage is lodged with NSW Land Registry Services instead of Titles Queensland. NSW has required land dealings, including mortgages and discharges, to be lodged electronically since 11 October 2021, according to the NSW Registrar General, so the border makes no difference to speed. Our Sydney and NSW page has more on how NSW titles work.
Worked example: a Yatala manufacturer and a container of stock
Not a real client; a simplified illustration with round figures.
A Yatala business that makes outdoor furniture has a large retail order confirmed, but its overseas supplier wants payment before shipping. The owners need $260,000 for about a season.
Their factory unit in Yatala is worth about $2.2m with $1.1m owing. They prefer to leave their home out of it. We lend $260,000 plus costs on a registered second mortgage over the factory. The valuer inspects within two days, the directors sign, the mortgage is registered with Titles Queensland and the supplier is paid. When the retailer pays for the delivered order, the loan is cleared and the release goes through. A matter of months, start to finish. If timing like this matters to you, our Brisbane page shows how a file moves day by day.
Holding Gold Coast property? See what it can support
From a Coomera family home to a Broadbeach apartment or a Molendinar shed, you start the same way. The form is short, about a minute of your time, and making an enquiry does not run a credit check. We don’t hand your details to a queue of other lenders. A real person here reviews what you send and rings you.
Accuracy helps us help you: give the exact address, whether it’s on the Queensland or NSW side, what kind of property it is (house, unit, factory), the balance owing and the date the funds are needed.
Frequently asked questions
Do you write caveat loans on the Gold Coast?
On Gold Coast property we use a short-term registered second mortgage. It gives the same outcome as a caveat loan, business funds behind your bank, and is usually arranged just as quickly. Caveat loans are what we write on Victorian property.
Will you lend against a high-rise apartment in Surfers Paradise or Broadbeach?
Often, yes. The valuer looks at recent sales in the same building, the unit's size and layout, and whether it is tied to a holiday-letting pool. Standard residential units in established towers are the most straightforward.
Is a hotel-style or serviced apartment acceptable security?
It can be harder. Units bound to a letting pool or management rights arrangement have fewer buyers and less sales evidence, which narrows what can be lent against them. Tell us how the unit is used and we'll say quickly whether it works.
My home is in Tweed Heads. Is that treated differently?
Only in where the mortgage is lodged. Tweed is in NSW, so it is registered with NSW Land Registry Services rather than Titles Queensland. It is still a short-term registered second mortgage and moves at the same pace.
How long does a Gold Coast valuation take?
Houses and standard units are usually inspected within a day or two of being ordered. Prestige waterfront homes and unusual property can take a little longer because the valuer has fewer direct comparisons.